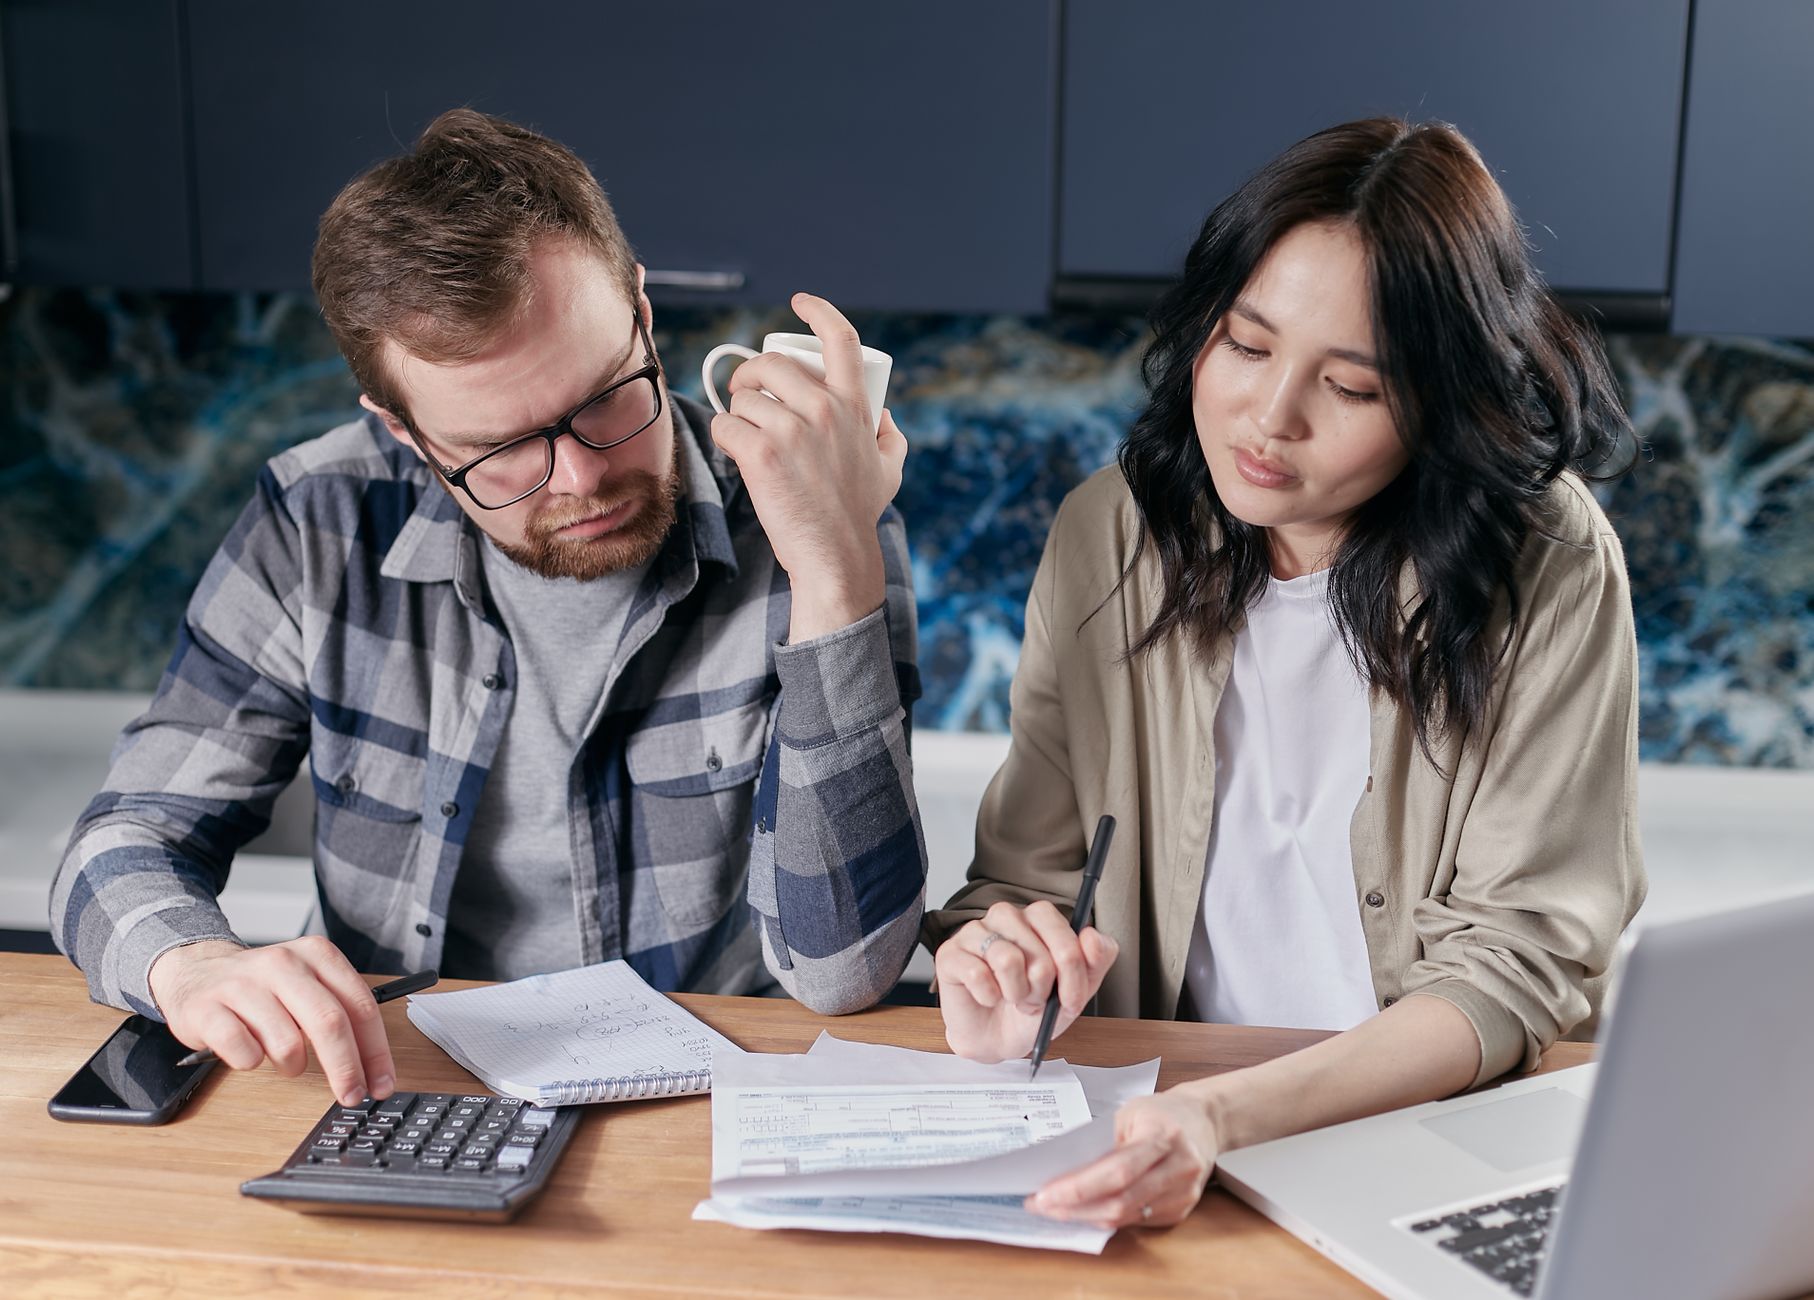
Debt is common, but that does not make it easy to manage. When several balances compete for your income each month, it can be hard to tell which payment matters most, how much interest is adding to the total, or whether a payoff plan is realistic. The good news is that most debt problems become clearer once they are organized. With the right information, a practical repayment method, and a plan that leaves room for real life, many borrowers can reduce stress and make steady progress.
Start by organizing every debt in one place
Before choosing a repayment strategy, build a complete debt inventory. Many people know roughly what they owe, but a workable plan requires details. Include each account, the current balance, annual percentage rate, minimum payment, due date, and whether the rate is fixed, variable, or promotional.
- Credit cards
- Personal loans
- Auto loans
- Student loans
- Medical bills
- Buy now, pay later balances
- Any debt owed to family or friends
A simple table can make priorities easier to see.
| Debt | Balance | APR | Minimum Payment | Due Date | Notes |
|---|---|---|---|---|---|
| Credit Card A | $600 | 19.99% | $30 | 8th | Smallest balance |
| Credit Card B | $3,000 | 28.99% | $90 | 14th | Highest interest rate |
| Medical Bill | $1,200 | 0% | $50 | 20th | Check hardship terms |
| Personal Loan | $4,500 | 10.50% | $100 | 27th | Fixed payment |
Once everything is listed, total your minimum payments and compare that number with your monthly income and essential expenses. If you cannot cover minimums consistently, the priority shifts from strategy to stabilization. That may mean contacting creditors, asking about hardship programs, or reviewing whether a nonprofit credit counseling agency could help structure payments.
Know what interest is really costing you
Interest is the price of carrying debt over time. Two balances of the same size can behave very differently depending on the rate. A $3,000 credit card balance at 24% APR has a monthly rate of about 2%, so carrying that balance for one month can add roughly $60 in interest before new purchases or fees. If the rate is higher, the balance can grow even faster.
It also helps to understand a few common details:
- APR: The annual percentage rate shows the yearly cost of borrowing, but interest often accrues daily or monthly.
- Variable rates: These can rise as broader interest rates change, increasing monthly finance charges.
- Promotional rates: A 0% offer can be helpful, but the rate may jump sharply once the introductory period ends.
- Late fees and penalty APRs: Missing a due date can raise costs quickly and damage credit.
Minimum payments can create the illusion of progress while extending repayment for years. On high-interest revolving debt, a large share of the minimum may go toward interest rather than principal. That is why an organized payoff strategy matters: extra dollars directed to the right balance can shorten the timeline significantly.
Choose a repayment method that matches your goals and behavior
Two of the most common approaches are the debt snowball and the debt avalanche. Both require making minimum payments on all debts and putting any extra money toward one target balance at a time. The difference is how the target is chosen.
| Method | How It Works | Main Benefit | Best Fit For |
|---|---|---|---|
| Debt Snowball | Pay extra toward the smallest balance first, regardless of rate | Faster psychological wins | People who stay motivated by visible progress |
| Debt Avalanche | Pay extra toward the highest-interest balance first | Usually lowers total interest cost | People focused on efficiency and long-term savings |
Neither method is automatically right for everyone. A borrower who has quit and restarted several payoff plans may benefit more from the motivation of early wins. Someone with large credit card balances at very high rates may prefer the mathematical efficiency of prioritizing interest cost first.
Example: how strategy can affect your timeline and total cost
Assume a borrower has the four debts listed above and can pay $500 per month in total. The required minimums add up to $270, leaving $230 each month to direct toward a target balance. The estimates below assume no new charges, rates stay the same, and all payments are made on time.
| Approach | Target Order | Estimated Payoff Time | Estimated Interest and Fees |
|---|---|---|---|
| Debt Snowball | Credit Card A, Medical Bill, Credit Card B, Personal Loan | About 23 months | About $1,980 |
| Debt Avalanche | Credit Card B, Credit Card A, Personal Loan, Medical Bill | About 21 months | About $1,420 |
In this example, the avalanche saves about $560 and shortens repayment by roughly two months because it attacks the 28.99% balance first. But the snowball eliminates one account almost immediately, which can make the plan feel more achievable. If motivation has been the main obstacle in the past, that early success may be worth the added cost.
There are also situations where the numbers do not tell the whole story. A 0% medical bill may look safe to leave for later, but if the account could be sent to collections or a hardship agreement is about to expire, it may deserve earlier attention. Good repayment plans combine math with real-world account terms.
Build a repayment plan you can actually keep
The best strategy is the one you can follow month after month. An aggressive plan that depends on perfect spending rarely lasts. A sustainable plan usually includes the following steps:
- Set a monthly debt budget. Decide how much can realistically go to debt after housing, food, insurance, transportation, and utilities.
- Automate minimum payments. This reduces the chance of late fees and credit damage.
- Choose one target balance. Apply every extra dollar there until it is paid off.
- Redirect freed-up payments. When one account is gone, roll that payment into the next target.
- Review the plan monthly. Income changes, rate changes, and unexpected expenses may require adjustments.
For example, suppose a household can afford an extra $200 in a normal month, but overtime income is unpredictable. Rather than assuming that extra cash will always be available, it may be smarter to build the plan around $125 and treat any additional amount as a bonus payment. That produces a slower but more reliable path.
Small tactical changes can also help. Moving due dates closer to payday, removing stored card numbers from shopping apps, and using alerts for statement balances can reduce the chance of new debt replacing old debt.
Balance debt payoff with savings
Paying debt as fast as possible sounds appealing, but using every spare dollar for repayment can backfire if one emergency pushes the household back onto credit cards. In many cases, it makes sense to build a modest cash buffer while also paying down high-interest debt.
| Situation | Starter Savings Goal | Why It Helps |
|---|---|---|
| Stable income, few dependents | $500 to $1,000 | Covers many routine surprises without adding new debt |
| Variable income or older vehicle | At least one month of essential expenses over time | Provides more protection against income gaps and repairs |
| Employer retirement match available | Consider contributing enough to get the full match | A full match can be more valuable than extra low-interest debt payments |
In practice, many borrowers use a blended approach: keep building a small emergency fund, pay minimums on all debts, and focus extra payments on the highest-priority balance. Once expensive debt is under better control, savings can take a larger share of the budget.
Consider tools that may lower repayment costs
Repayment strategies work best when the debt itself is manageable. In some cases, restructuring the debt may reduce total cost or make payments easier to track. That does not eliminate the need for budgeting, but it can improve the odds of success.
| Option | When It May Help | What to Watch For |
|---|---|---|
| Balance transfer card | High-rate credit card debt and strong enough credit to qualify | Transfer fees, short promotional periods, higher rate after the offer ends |
| Debt consolidation loan | Multiple high-rate balances and a lower fixed rate is available | Origination fees, longer repayment term, new debt if cards are reused |
| Hardship program | Temporary income loss, illness, or other financial disruption | Terms vary; relief may be temporary and could affect account status |
| Nonprofit credit counseling | Difficulty keeping up with several accounts at once | Make sure the organization is reputable and fees are clearly explained |
These tools can be useful, but they work best when paired with changes in spending habits. Consolidating credit card debt into a lower-rate loan does not help much if the cards are immediately run back up.
Avoid the debt mistakes that keep balances around longer
Many debt problems are not caused by one large decision but by several small patterns repeated over time. Common mistakes include:
- Paying only the minimum without a strategy. This often stretches repayment far longer than expected.
- Ignoring due dates. Late fees, penalty rates, and credit score damage can make progress harder.
- Using savings down to zero. Without even a small emergency cushion, new borrowing often follows.
- Continuing to use cards heavily during payoff. New balances can cancel out months of progress.
- Choosing a lower monthly payment without looking at total cost. A longer term may increase total interest significantly.
- Waiting too long to ask for help. Creditors are often easier to work with before accounts become seriously delinquent.
One common example involves a borrower who takes out a consolidation loan, feels temporary relief, and then uses credit cards again for routine expenses. The result is both the new loan payment and renewed card balances. A safer approach is to pair consolidation with a strict spending plan, reduced credit limits if needed, and automatic transfers to savings for expected irregular expenses such as car repairs or annual insurance premiums.
Conclusion: practical steps to regain control
Debt is easier to manage when it is visible, prioritized, and tied to a plan that fits your real budget. Start by listing every balance, rate, minimum payment, and due date. Learn which debts are costing the most in interest and choose a repayment approach that fits both your numbers and your behavior. If motivation is the biggest hurdle, the snowball may help you stay engaged. If cutting interest is the top goal, the avalanche will often save more money.
Just as important, build a plan that leaves room for stability. A small emergency fund, on-time payments, and realistic monthly targets can prevent setbacks from turning into new debt. If your current payments are unmanageable, contact creditors early and review whether consolidation, hardship options, or nonprofit counseling could help. The main lesson is that progress does not require perfection. It requires clear information, steady decisions, and a repayment plan you can keep following until the balances are gone.
Recommended Partner Guides
Guiscard M. is the founder and editor of MoneyLendings.com – a financial education platform focused on helping consumers better understand credit, debt, loans, and personal finance decisions. With over 25 years of experience in finance and insurance, he brings practical knowledge of lending, credit, debt management, and personal finance to create useful tools, calculators, and educational resources that simplify complex financial topics.
Combining this experience with expertise in web development and digital content creation, Guiscard focuses on making financial information easier to understand and more accessible.