Getting approved for business financing is often less about luck and more about preparation. For many U.S. entrepreneurs, the process feels intimidating because lenders look at both business health and, in many cases, the owner’s personal finances. Understanding how to get a small business loan starts with knowing what lenders want to see: steady revenue, manageable debt, acceptable credit, organized records, and a clear reason for borrowing. Whether you need working capital, equipment, inventory, or money to expand, the strongest applications show that the loan will support growth rather than cover a long-term cash shortfall.
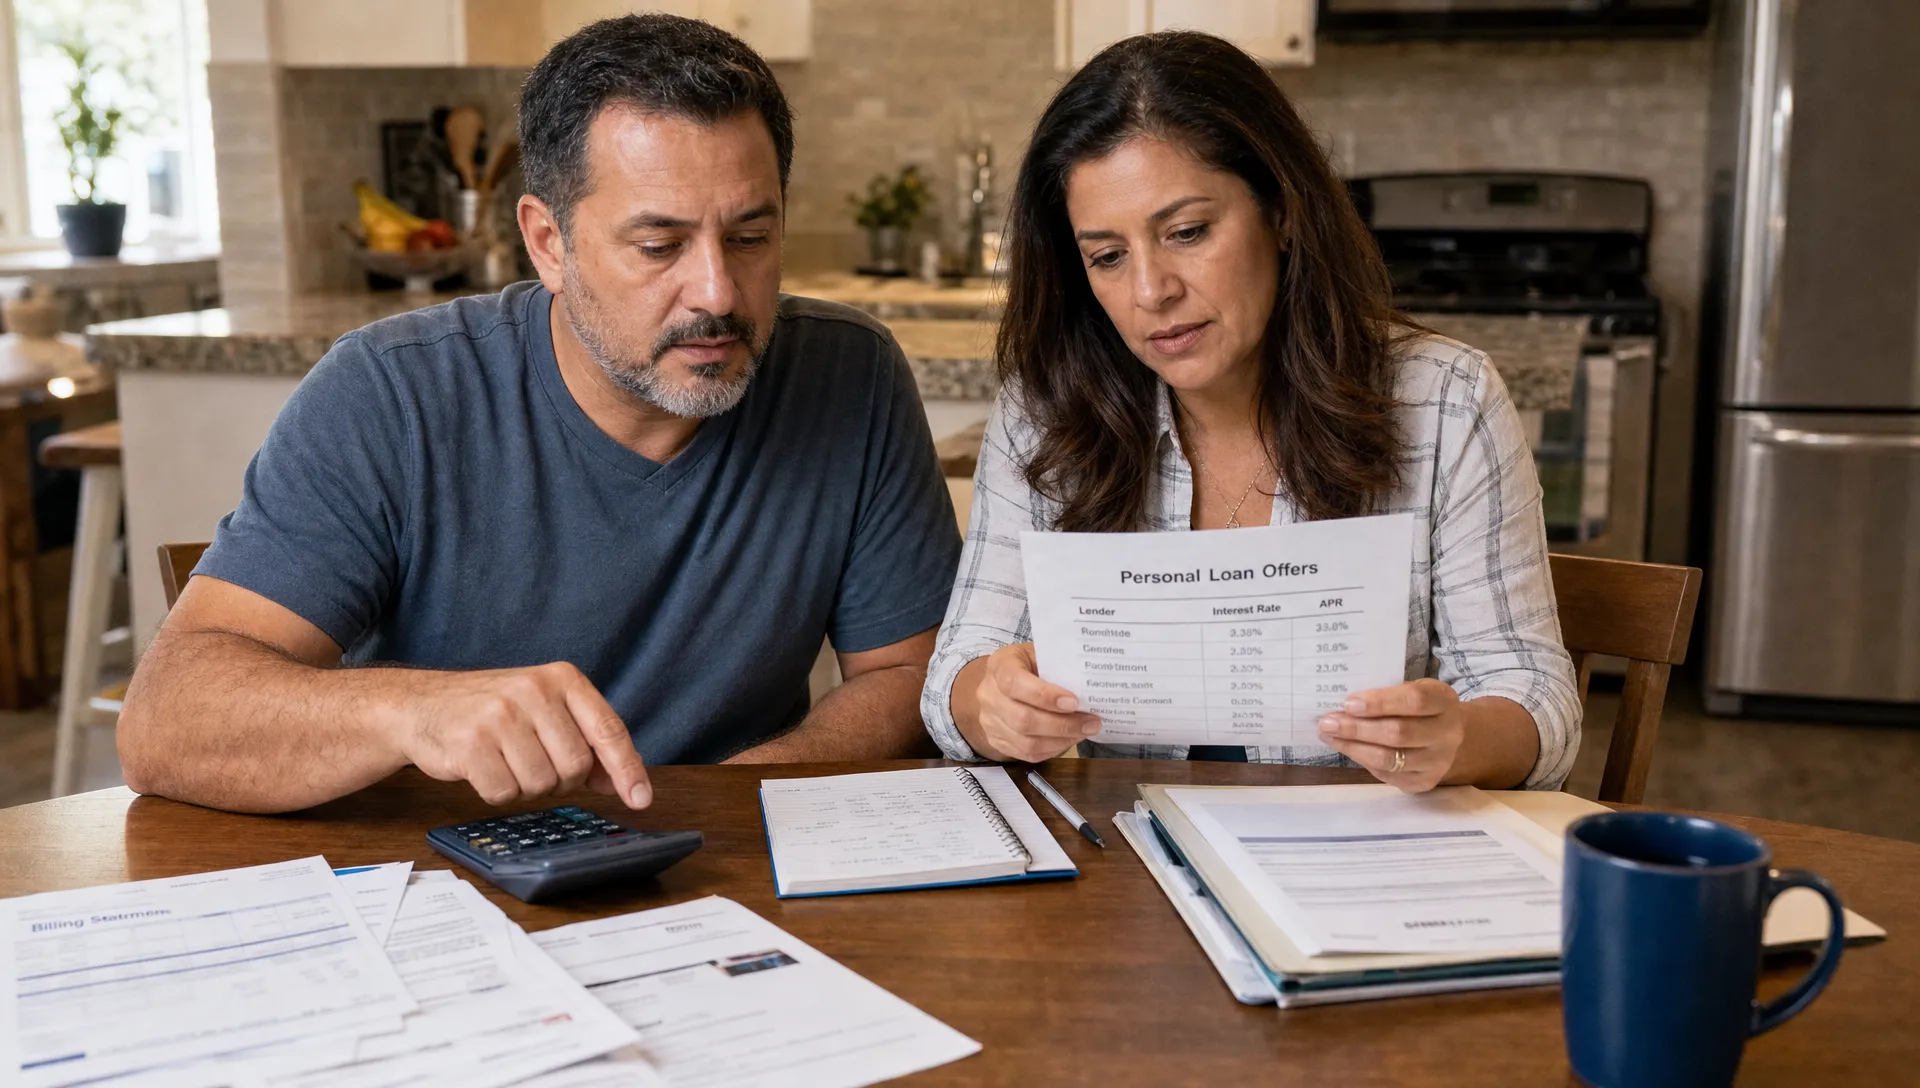
From a financial education perspective, it helps to think of a business loan the same way you would any major credit decision. The amount you borrow should fit your budget, the payment should be affordable during slow months, and the debt should move your business forward. Lenders may review your personal credit score, tax returns, bank statements, and debt obligations, especially if your business is new or closely tied to your household income. That means your business plan and your personal money habits can both affect the outcome.
Smart borrowing rule: Before applying, estimate the monthly payment and compare it with average monthly net cash flow. If a payment only works in your best sales month, the loan may be too large or too expensive.
Choose the right type of small business financing
The first step is matching the loan product to your actual need. A long-term loan may work for expansion or large equipment purchases, while a line of credit can be better for seasonal gaps or short-term working capital. SBA loans usually offer competitive terms, but they can require stronger documentation and more time. Online lenders may fund faster, but rates can be higher. Business credit cards can help with smaller recurring expenses, though carrying a balance can become costly.
Picking the wrong loan can create unnecessary debt pressure. For example, using a short-term loan to finance a project that will not generate returns for a year can strain cash flow. On the other hand, stretching a small short-term need into a long repayment period may increase total interest paid. Good financial education means comparing cost, speed, collateral requirements, and monthly payment impact before signing anything.
| Financing option | Typical use | Funding speed | Common qualification focus |
|---|---|---|---|
| SBA loan | Expansion, equipment, refinance, working capital | Usually 30-90 days | Good credit, strong records, repayment ability |
| Bank term loan | Established businesses with predictable revenue | Usually 2-8 weeks | Credit, cash flow, time in business, collateral |
| Online term loan | Fast working capital or short-term projects | Usually 1-5 business days | Revenue trends, bank activity, basic credit review |
| Business line of credit | Seasonal needs, payroll gaps, inventory | A few days to a few weeks | Cash flow stability and revolving debt management |
| Equipment financing | Vehicles, machinery, tools, technology | Usually 2-7 business days | Equipment value, credit, down payment |
| Business credit card | Small purchases, travel, recurring expenses | Same day to 2 weeks | Personal credit and income |
What lenders review before they approve a loan
Lenders want evidence that your business can repay the debt. One of the biggest factors is cash flow. A profitable business on paper can still be denied if deposits are inconsistent or existing debt payments already consume too much income. Many lenders calculate a debt service coverage ratio, or DSCR, to measure whether cash flow is strong enough to cover the new payment. In simple terms, they want a cushion, not a break-even budget.
Credit matters too. Established businesses may have a business credit file, but many lenders also check the owner’s personal credit score, especially for small businesses, startups, and sole proprietors. Late payments, high credit utilization, recent collections, or heavy personal debt can hurt your odds. If your credit needs work, paying down revolving balances and correcting report errors before you apply can make a real difference.
Documentation is another major piece of the decision. Most lenders ask for some combination of business and personal tax returns, recent bank statements, profit and loss statements, balance sheets, articles of organization, business licenses, and an Employer Identification Number. If your loan is for expansion, they may also want a business plan, financial projections, or purchase quotes for equipment. The more complete and consistent your records are, the more credible your application looks.
Pre-application checklist
Review personal and business credit reports, separate business and household spending, reconcile bank statements, update your budget, and calculate how much you truly need. Borrowing extra
Guiscard M. is the founder and editor of MoneyLendings.com – a financial education platform focused on helping consumers better understand credit, debt, loans, and personal finance decisions. With over 25 years of experience in finance and insurance, he brings practical knowledge of lending, credit, debt management, and personal finance to create useful tools, calculators, and educational resources that simplify complex financial topics.
Combining this experience with expertise in web development and digital content creation, Guiscard focuses on making financial information easier to understand and more accessible.